The Homeowner With a Flooded Basement Isn't Waiting for Your Voicemail
Emergency calls ring your on-call phones. If nobody answers, your team gets an alert. Calls, texts, claim quotes, and invoices stay on the customer record.
On this page · 9
- It's 2 a.m. There's Water in the Basement.
- Emergency Calls and Routine Leads Get Different Responses
- From Mitigation to the Final Payment
- What's Waiting on the Adjuster?
- See Which Sources Bring Paid Restoration Jobs
- Pass On the Work You Don't Do
- What Stays With Your Team and the Insurer
- Who Does What on a Restoration Job
- Talk Through Your Restoration Jobs
It's 2 a.m. There's Water in the Basement.
The homeowner finds three restoration companies on a phone.
They need someone to answer and tell them what happens next. They aren't planning to fill out an estimator and wait for tomorrow.
When nobody answers, the homeowner calls the next company on the list.
Your business number rings every phone on your on-call team at once, day or night. Who carries a phone after hours is your decision.
If nobody answers, the whole on-call team gets an alert to return the emergency call. Someone still needs to call back.
Your team decides who drives out and when. See what happens to a missed call
Every call, answered or missed, lands on the homeowner's customer record. A mitigation lead from a plumber's referral doesn't sit in one crew member's call log.
I build your website pages for the emergencies you handle, such as basement flooding, burst pipes and fire damage. On a phone, your number is one tap away on every page.
Emergency Calls and Routine Leads Get Different Responses
Most contractor leads can wait an hour. A homeowner pricing a deck sends a form at night and compares quotes over the next two weeks.
How a routine lead and an emergency restoration call differ.
| Inquiry | Routine lead | Emergency water or fire call |
|---|---|---|
| How it arrives | An online estimate or a website form | A phone call, often at night or on a weekend |
| What the homeowner wants first | A price range and a time to talk | Someone on site today |
| First response | Automatic follow-ups on the schedule you approve | Your on-call crew answers the phone |
| How the price is set | Your online estimate, then your quote | Your inspection, then a claim quote and the homeowner's quote |
| Who decides on payment | The homeowner | The insurer and the homeowner |
Routine leads get automatic follow-ups. An emergency call rings your crew.
From Mitigation to the Final Payment
Once your crew is on site, each step names what the Growth Engine handles and what stays with your team.
1. Your Crew Assesses the Site
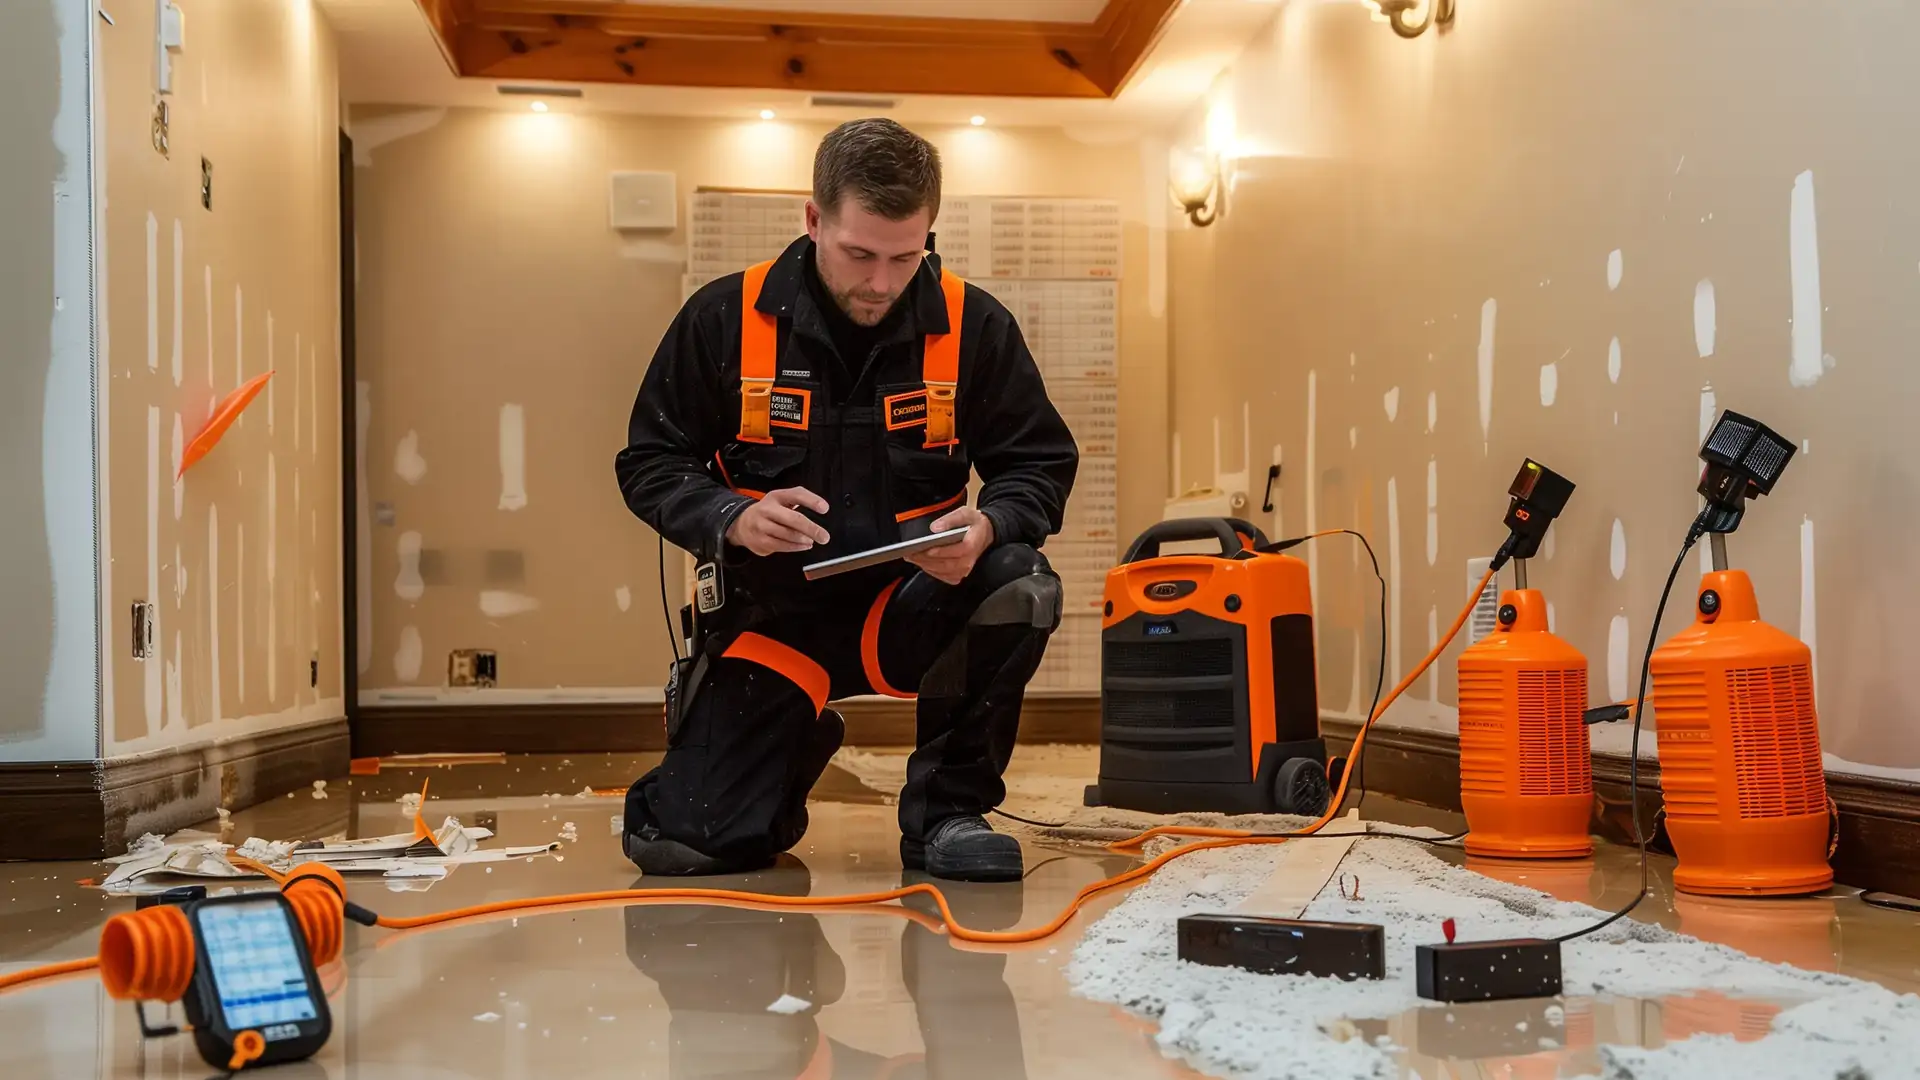
Your crew inspects the damage, starts mitigation, and records what it finds. Moisture readings, drying logs and measuring tools stay the ones you use now.
The visit sits on the homeowner's customer record, next to every call before it.
2. Photos and Messages Stay on One Record
Mitigation crews take photos all day of standing water, cut lines and drying equipment. Those photos usually end up spread across several phones.
Texts to and from your business number stay on the customer record, photos included. Calls, voicemails and call recordings sit there too.
When the adjuster asks what happened on day two, the texts and photos from day two are on one record.
Photo reports for the insurer stay in your current tools.
3. The Adjuster and the Homeowner Each Get a Quote
Your team enters the inspection once. From it, the Growth Engine builds a claim quote for the adjuster and a plain quote for the homeowner.
Your team checks the claim quote and sends it, and the insurer decides what it covers. See how claim quotes work
The online estimator serves planned work, such as finishing the basement after the claim closes.
4. The Homeowner Hears From You Until the Work Is Done
A claim can wait weeks on the adjuster, and the homeowner calls for updates the whole time.
Whoever answers sees both quotes, every call and text, and each visit on the customer record. A call recording settles what was said.
5. The Job Gets Paid
When the insurer approves and the homeowner signs, you mark the quote Advanced and enter the crew size and days.
When you mark the job Complete, the Growth Engine builds the invoice from the homeowner's signed quote and sends reminders until the balance is paid. Splitting a payment between the insurer and the homeowner's deductible stays in your current process.
What's Waiting on the Adjuster?
Five claims can sit with five adjusters at once. Each claim quote stays open on your quote list until you mark the next step, so you see which jobs still wait on the insurer.
Example of open claim quotes on your quote list.
| Homeowner | Job | Claim quote sent | Amount |
|---|---|---|---|
| R. Patel, Oshawa | Basement flood from a sewer backup | 21 days ago | $18,640 |
| M. Chen, Whitby | Burst pipe through a kitchen ceiling | 9 days ago | $7,310 |
| D. Okafor, Ajax | Smoke damage after a kitchen fire | 4 days ago | $26,950 |
Detailed claim statuses, such as a supplement under review, stay in your current tools. So do emergency dispatch and drying logs.
The Growth Engine is the same managed service every trade gets, set up for how a restoration job runs.
See Which Sources Bring Paid Restoration Jobs
Restoration work comes from Google searches, plumber and insurer referrals, and past customers. Some sources bring calls that never turn into paid jobs.
The Growth Engine follows each customer from the search, ad or referral that brings them in to the payment on their job, and shows the revenue each source produces. See contractor marketing revenue tracking
Pass On the Work You Don't Do
After a flood, the homeowner often wants more than the repair, like a new kitchen or the basement finished the way they always meant to. That work sits outside the claim, and often outside your trade.
With the homeowner's agreement, flag it on their customer record and pick the trade. The Growth Engine sends it to the company on that trade's shared website that serves the job's address, and that company contacts the homeowner.
When the homeowner pays that job in full, you get $100 off your next bill. The company that does the work pays the normal shared-website fee on it. Read the referral rules.
What Stays With Your Team and the Insurer
- Emergency dispatch and on-call schedules
- Site inspections and mitigation work
- Moisture readings, drying logs and photo reports for the insurer
- Mitigation and reconstruction schedules
- Sending claim quotes and supplements to the adjuster
- Coverage decisions and claim approvals, which belong to the insurer
- Claim numbers and adjuster details as their own fields
- Detailed claim statuses, such as a supplement under review
- Splitting a payment between the insurer and the homeowner's deductible
If one of these decides whether the Growth Engine fits your business, raise it on the call. You get a straight answer before you sign anything.
Who Does What on a Restoration Job
Who handles each step of a water or fire restoration job.
| Step | Who handles it |
|---|---|
| Build website pages for the emergencies you handle | Me |
| Ring every crew phone on an emergency call | Growth Engine |
| Answer the call and decide who drives out | Your team |
| Inspect the damage and run mitigation | Your crew |
| Keep calls, texts, photos and visits on the customer record | Growth Engine |
| Write the repair estimate and check prices | Your team |
| Build the claim quote and the homeowner's quote | Growth Engine |
| Send the claim quote, talk to the adjuster and prepare supplements | Your team |
| Decide what the policy covers and pays | Insurer |
| Mark the quote Advanced and the job Complete | Your team |
| Send the invoice and payment reminders | Growth Engine |
| Show which sources bring paid jobs | Growth Engine |
| Set up the Growth Engine for restoration work | Me |
Talk Through Your Restoration Jobs
Review How My Emergency Calls Are Handled. In an hour, I walk through how an emergency call becomes a paid job in your business today. You talk to me, the person who sets up and runs the Growth Engine.
The restoration founding spot is open. The first restoration company builds its website with me at no charge during development, the way Darteno did for interlock. See the Founding Contractor Program
Common Questions From Canadian Restoration Contractors
How do we stop losing emergency calls at night?
Your business number rings every phone on your on-call team at once, day or night, and whoever is free answers. A missed call alerts the whole on-call team, so someone calls the homeowner back before they try the next company. Who carries a phone after hours is your decision. See what happens to a missed call.
Is there a way to dispatch our emergency crew from the Growth Engine?
Dispatch stays with your team. The call reaches whoever is on call, and your team decides who drives out.
How do we keep job photos from getting lost across crew phones?
Photos texted to or from your business number stay on the customer record with the text. Photo reports for the insurer stay in your current tools.
Does the Growth Engine connect to our insurers or estimating software?
No. Your team sends the claim quote to the adjuster as a PDF, and the insurer keeps using the program it names. See how claim quotes work.
Is there a way to run drying and reconstruction schedules in the Growth Engine?
Drying logs, mitigation schedules and reconstruction schedules stay in your current tools. Once the homeowner approves, your team enters the crew size and days on the customer record.
How do we answer a homeowner who calls for a claim update?
Whoever answers sees both quotes, every call and text, and each visit on the homeowner's customer record. Your quote list shows which claims still wait on the adjuster.
Can we split an invoice between the insurer and the homeowner's deductible?
That split stays in your existing process. The Growth Engine invoices from the homeowner's signed quote.
Do we need separate software for our regular renovation work?
The same Growth Engine app runs both. A private-pay job uses a standard contractor quote and automatic follow-ups. A claim job adds a claim quote for the adjuster, built from the same estimate as the homeowner's quote.